If you’re considering selling your life insurance policy, you may be wondering, is a life settlement legal? While receiving cash for a life insurance policy may sound too good to be true, life settlements are legitimate, well-established financial transactions. They are legal in all 50 states and regulated in most states, with laws designed to protect policy owners and establish standards for companies conducting these transactions. In fact, the legal foundation for selling an existing life insurance policy dates back more than a century.
Are Life Settlements Legal in All 50 States?
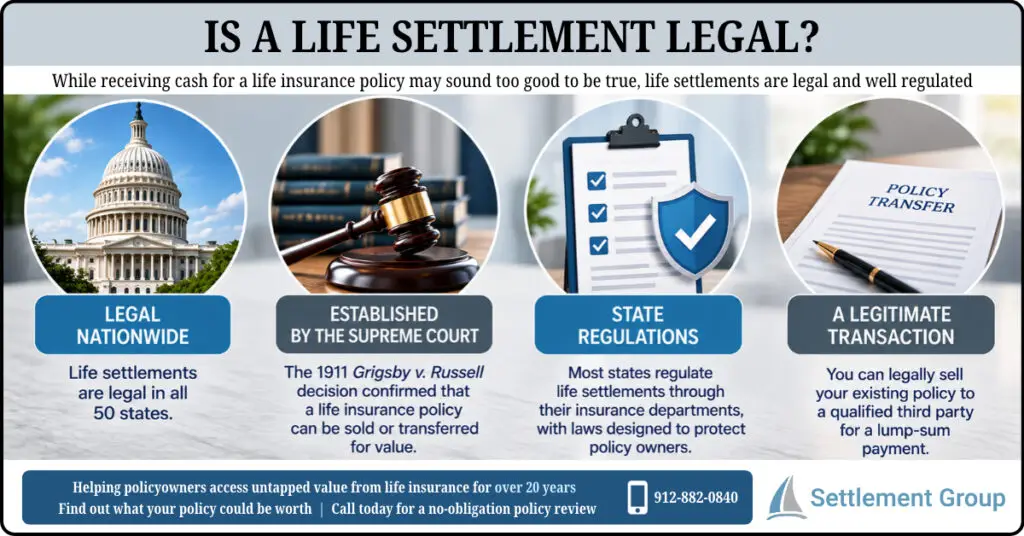
Life settlements are legal in all 50 states. Most states have established licensing requirements, consumer protections, and procedures governing life settlements. Some states regulate both traditional life settlements and viatical settlements, while others have laws addressing only certain types of transactions.
Because the regulations differ, the policy owner’s state of residence is an important factor in determining which requirements apply. State laws may establish rules concerning provider licensing, mandatory disclosures, privacy protections, waiting periods, and the right to cancel a completed transaction. Policy owners should work with a provider familiar with the applicable requirements in their state.
When Did Selling a Life Insurance Policy Become Legal?
The legal foundation for life settlements dates back to 1911, when the United States Supreme Court decided Grigsby v. Russell. This landmark case established an important principle: a legitimately issued life insurance policy could be transferred to another person for compensation, even when the purchaser did not have an insurable interest in the insured’s life.
The case involved John Burchard, who needed money for a surgical procedure and sold his existing life insurance policy to Dr. A. H. Grigsby for $100. Grigsby also agreed to pay the policy’s future premiums. After Burchard died, a dispute arose over whether Grigsby was entitled to the death benefit because he had no insurable interest in Burchard’s life.
In its December 4, 1911, decision, the Supreme Court ruled that the assignment of the valid policy was lawful. Writing for the Court, Justice Oliver Wendell Holmes Jr. recognized that life insurance policies should possess the ordinary characteristics of property, including the ability to be sold or transferred. The decision distinguished between purchasing a valid, existing policy and taking out insurance on another person’s life without an insurable interest.
This ruling became an important legal foundation for the secondary market for life insurance. Although the modern life settlement industry developed decades later, Grigsby v. Russell established that policy owners could receive compensation for transferring legitimate life insurance coverage. The ability to sell a policy is therefore not a recent development, but a property right recognized by the nation’s highest court more than 100 years ago.
Who Regulates Life Settlement Companies?
Life settlement provider companies are primarily regulated at the state level, with oversight handled by state insurance departments. In states with applicable legislation, providers must meet licensing and compliance requirements before conducting regulated transactions. These requirements may include maintaining appropriate records, providing disclosures, protecting confidential information, and following established procedures for transferring policy ownership.
The National Association of Insurance Commissioners (NAIC) has developed model legislation addressing life and viatical settlements, which states can use when establishing their own regulatory frameworks. However, individual states determine which provisions to adopt and how those laws are enforced. This means a transaction that is permissible in one state may be subject to different documentation, timing, or disclosure requirements in another.
What Legal Protections Do Life Settlement Sellers Have?
State life settlement regulations are intended to protect policy owners throughout the transaction. These protections may include written disclosures explaining the terms of the sale, potential tax consequences, effects on government benefits, and alternatives to selling the policy. Sellers should receive sufficient information to understand the financial implications of transferring ownership and giving up the policy’s future death benefit.
Privacy is another important consideration because evaluating a life insurance policy often requires medical records and detailed policy information. Many states also provide a rescission period during which a seller can cancel a completed transaction, subject to specific deadlines and conditions. The length of this period varies by state, and exercising the right to cancel requires returning the settlement proceeds.
Licensing provides an additional layer of oversight in states where it is required. Policy owners can generally verify whether a life settlement provider is properly licensed through their state insurance department before proceeding with a transaction.
Is It Legal to Sell a Life Insurance Policy to Someone Other Than the Insurance Company?
A life insurance policy is an asset that can be sold like anything else you own. When a qualifying policy is sold through a life settlement, the purchaser becomes the new owner and beneficiary, assumes responsibility for future premium payments, and receives the death benefit when the insured passes away. The original policy owner receives a lump sum payment in exchange.
This is different from surrendering a policy to the insurance company. Surrendering a policy terminates the coverage in exchange for any available cash surrender value, while a life settlement transfers ownership to another party and keeps the policy in force. A life settlement offer is less than the death benefit, but may be significantly higher than the policy’s cash surrender value, depending on the insured’s age and health, future premiums, and other policy characteristics.
Are There Restrictions on When a Life Insurance Policy Can Be Sold?
Although selling an existing life insurance policy is legal, state laws may restrict how soon a policy can be sold after issuance. Many states establish waiting periods intended to discourage individuals from purchasing coverage primarily for resale to investors. The required waiting period varies by jurisdiction, and exceptions may apply in circumstances such as certain changes in health, employment, or financial circumstances.
The policy’s contestability period is also an important consideration. This period typically lasts for the first two years after a policy is issued, during which the insurance company may have broader rights to investigate statements made in the original application. Policies cannot be sold through a life settlement during this initial period. Ownership arrangements, policy provisions, and other circumstances may also affect eligibility, making an individual policy review important.
How Can I Tell if a Life Settlement Company Is Legitimate?
Before selling a life insurance policy, verify that the company is authorized to conduct the transaction and provides clear information about its role. In states requiring provider licensing, the company’s state licenses can be confirmed through the state insurance department.
Policy owners should review the purchase agreement, required disclosures, and ownership transfer documents carefully. Because the transaction involves confidential medical and insurance information, the provider should obtain appropriate authorizations and explain how that information will be used. Sellers should also understand the payment procedures, including when funds will be released. Once the ownership transfer has been completed and confirmed, payment is issued.
Is a Life Settlement Legal Without Using a Broker?
Policy owners can legally work directly with a life settlement provider without hiring a broker. A provider evaluates policies, makes or facilitates purchase offers, arranges funding, and coordinates transactions through closing. A broker, by comparison, represents the policy owner and seeks offers from providers in exchange for compensation. Brokers do not purchase the policies themselves.
In states that regulate life settlements, providers and brokers may each be subject to licensing and disclosure requirements. Broker compensation is typically deducted from the transaction proceeds and can sometimes represent 30% or more of an offer. Working directly with a provider company eliminates a separate broker fee, allowing policy owners to evaluate an offer without that additional deduction.
Are Life Settlement Proceeds Taxable?
Life settlement proceeds may be subject to federal income tax, depending on the policy and the circumstances of the sale. Tax treatment can depend on the amount received, the policy owner’s investment in the contract, and other applicable factors. Viatical settlement proceeds are usually not subject to tax.
Receiving settlement proceeds may also affect eligibility for Medicaid or other means-tested government benefits because the payment can change an individual’s financial circumstances. Policy owners should consult qualified tax, legal, or benefits professionals.
Sell Your Life Insurance Policy with a Licensed Provider
Life settlements are a legal option for qualifying policy owners who no longer need, want, or can afford their existing life insurance coverage. State regulations provide an established framework for these transactions, including licensing requirements, disclosure obligations, and consumer protections where applicable. Understanding those requirements and working with an appropriately licensed provider can help policy owners approach the sale with greater confidence.
Settlement Group is a licensed life settlement provider that works directly with policy owners to help them access the value of their existing life insurance coverage. With more than 20 years of experience in the life settlement industry, our team evaluates policies, presents competitive offers, coordinates funding, and oversees the transaction through closing. We provide clear guidance throughout the process, helping policy owners understand their options and make informed decisions.
Contact Settlement Group today for a no-obligation policy review. 754-296-9034