If you’re searching for companies that buy life insurance policies, you’re most likely looking for a life settlement provider. These companies evaluate existing policies and may make or facilitate an offer to purchase them. But not every company involved in a life settlement serves the same role, and knowing whether you’re dealing with a licensed provider, a broker, or another intermediary can make a significant difference in how your policy is sold.
Before submitting your policy, it helps to understand what a life settlement provider does, how companies evaluate policies, and what to look for when choosing a company.
What Companies Buy Life Insurance Policies?
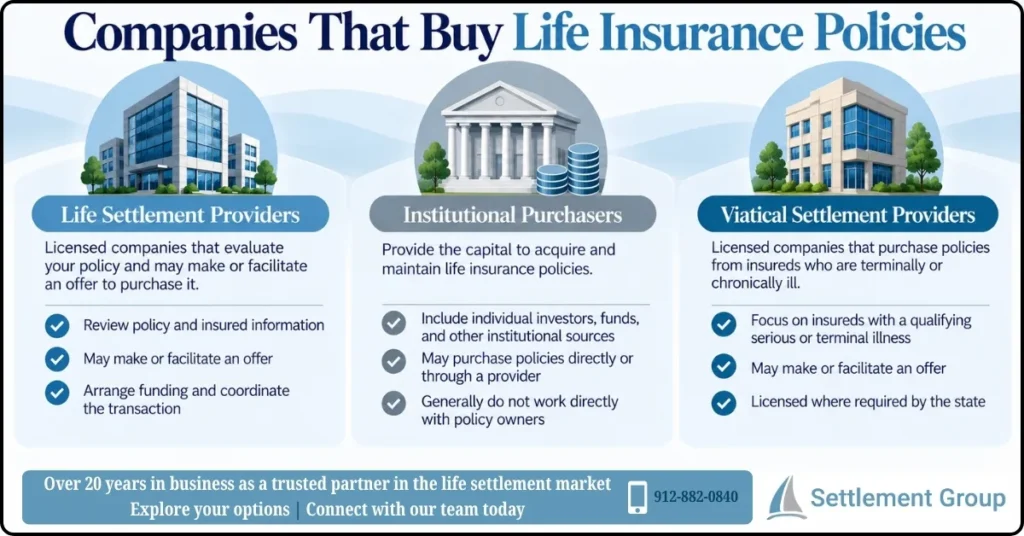
Companies that purchase existing life insurance policies are generally known as life settlement providers. A provider is on the purchasing side of a life settlement transaction and works directly with policy owners or through life settlement brokers.
The provider reviews the policy and information about the insured to determine whether the policy qualifies and whether an offer can be made. Providers may acquire policies for their own account or work with other purchasers or financing sources to fund transactions.
Life settlement providers should not be confused with the insurance companies that originally issued the policies. The insurance carrier continues to administer the policy, but it does not purchase the policy from you as part of a life settlement.
Are Companies That Buy Life Insurance Policies Called Providers?
In most cases, yes. A life settlement provider is the licensed entity involved on the purchasing side of the transaction.
However, you may encounter several types of companies when searching online for someone to buy your policy. Some websites belong to providers, while others belong to brokers, agents, lead-generation companies, or other intermediaries.
Before providing personal, medical, or policy information, find out what role the company actually plays. If it identifies itself as a life settlement provider, you can verify its licensing with your state insurance department.
Do Life Settlement Providers Buy Policies Directly?
Policy owners can work directly with a life settlement provider. A broker is not required for every life settlement transaction.
When you contact a provider directly, the provider evaluates your policy, obtains the information necessary to determine its potential value, and may present an offer if there is purchasing interest. If you accept the offer, the provider coordinates the documentation, funding, and closing process.
Working directly with a provider also means there is no separate broker fee deducted from your settlement proceeds.
What Policies Are Life Settlement Companies Looking For?
Life settlement companies evaluate each policy individually, but certain characteristics can make a policy more likely to qualify.
Traditional life settlements most commonly involve insureds age 65 or older, although younger insureds may qualify based on their health. Policies generally have a death benefit of at least $100,000, and universal life, guaranteed universal life, whole life, survivorship, and some term policies may qualify.
Convertible term policies can sometimes be sold if they are still within the conversion period. If you are considering selling a term policy, it is important to have it evaluated before the conversion option expires.
The insured’s health is also an important part of the evaluation. A policy owner does not need to be terminally ill to qualify for a traditional life settlement, but typically, younger policy holders will not qualify without a health impairment.
How Do Companies Determine What Your Policy Is Worth?
There is no standard price that a company will pay for a life insurance policy. An offer is based on the specific policy and insured.
Companies generally evaluate the insured’s age and health along with the policy’s death benefit, premium requirements, guarantees, and other policy characteristics. Two policies with identical death benefits can receive very different offers because the cost of maintaining the policies and the circumstances of the insureds may be different.
An offer cannot be accurately determined from the death benefit alone. Medical records and detailed policy information are typically required before a company can complete its evaluation.
Should You Sell Through a Provider or a Broker?
A provider and a broker perform different roles in a life settlement.
A provider is on the purchasing side of the transaction. The provider evaluates the policy, makes or facilitates an offer, arranges funding, prepares the necessary documents, and coordinates the transaction through closing.
A broker represents the policy owner and seeks offers from life settlement providers. The broker receives compensation for providing that service, and that compensation is deducted from the settlement proceeds. Many times, broker fees can be 30% or more of your offer.
Policy owners can decide whether they prefer to work with a broker or approach a licensed provider directly.
How Can You Verify a Life Settlement Company Is Legitimate?
Life settlements are regulated at the state level, and licensing requirements vary. Before working with a company, verify that it holds the appropriate license in your state when one is required.
Your state insurance department can generally provide licensing information. You should also confirm the company’s legal name and whether it is acting as a provider, broker, or another type of intermediary.
What Should You Ask a Company Before Selling Your Policy?
Before moving forward, make sure you understand who you are working with and how the transaction will be handled. Useful questions include whether the company is a licensed provider or broker, whether you will pay any fees or commissions, what information will be required, and what happens if you decide not to accept an offer.
You should also understand who will coordinate the transaction after an offer is accepted and how you will be kept informed through closing. Receiving an offer does not obligate you to sell your policy.
Can You Get Offers from More Than One Life Settlement Company?
Policy owners can explore more than one option before deciding whether to sell. An offer from one company does not establish what every other purchaser may be willing to pay for the same policy.
However, submitting a policy to multiple companies yourself can become complicated if the same policy is being circulated through several sources. Before submitting information broadly, understand how each company intends to market or evaluate your policy and whether it has already been presented to the same potential purchasers.
The goal should be to understand your available options without unnecessarily distributing your personal, medical, and policy information.
Sell Your Life Insurance Policy Directly to Settlement Group
Settlement Group is a licensed life settlement provider that works directly with policy owners. We evaluate policies, arrange funding, present offers when available, and coordinate transactions through closing.
If you are considering selling a policy, you can contact us directly to find out whether it may qualify and what information is needed for an evaluation. There is no separate broker fee when you work directly with us, and requesting a policy review does not obligate you to accept an offer.
Contact us today for a no-obligation policy review. 912-882-0840