If you’re asking how much is my life insurance policy worth, the answer depends on what type of value you’re looking for. A policy has a death benefit, but that is not necessarily what the policy is worth today. It may also have a cash surrender value and, for qualifying policies, a potential life settlement value.
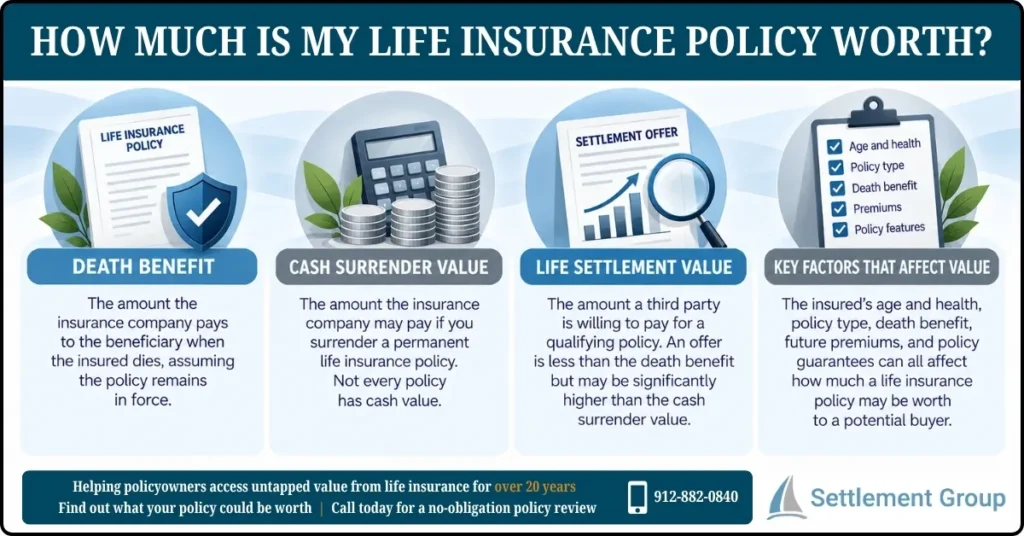
For policy owners considering a sale, the most important question is usually how much a buyer may be willing to pay for the policy. That amount cannot be determined from the death benefit alone. The insured’s age and health, future premiums, policy type, and guarantees can all affect its value.
What Is the Value of a Life Insurance Policy?
A life insurance policy can have several different values depending on what you plan to do with it.
The death benefit is the amount the insurance company pays to the beneficiary when the insured dies, assuming the policy remains in force.
The cash surrender value is the amount the insurance company may pay if the policy owner surrenders a permanent life insurance policy. Not every policy has cash value.
The life settlement value is the amount a third party may be willing to pay to purchase a qualifying policy. A life settlement offer is less than the death benefit but may be significantly more than the policy’s cash surrender value.
These numbers can be substantially different, so looking only at the face amount or cash value does not tell you what your policy might be worth if sold.
How Much Can I Sell My Life Insurance Policy For?
There is no standard percentage of the death benefit that a life insurance policy will sell for. Two $500,000 policies, for example, could have very different life settlement values.
A potential buyer needs to determine both the expected benefit of acquiring the policy and the cost of maintaining it. That requires information about the insured as well as detailed information from the insurance company.
For that reason, online estimates based on only your age and death benefit should not be treated as an actual offer. A meaningful valuation requires an individual review of the policy.
What Determines How Much My Life Insurance Policy Is Worth?
Several factors are considered when a life insurance policy is evaluated for a potential settlement.
Age and Health of the Insured
The insured’s age and current health are significant factors. Traditional life settlements are most commonly for insureds age 65 or older, although younger people may qualify depending on their health.
Medical records are reviewed as part of the evaluation. Changes in health since the policy was originally purchased can affect the policy’s settlement value.
Life Insurance Death Benefit
The policy’s death benefit is another important factor, but a larger death benefit does not automatically mean a proportionately larger offer.
Traditional life settlements generally involve policies with at least $100,000 in death benefit. Policies below that amount may sometimes qualify for a viatical settlement when the insured has a qualifying terminal illness. Because every case is different, please reach out with any questions rather than assuming your policy will not qualify.
Current and Future Premiums
A purchaser becomes responsible for premiums after acquiring a policy, so the cost required to keep the policy in force can significantly affect its value.
A policy requiring relatively low future premiums may be more attractive than a similar policy requiring substantially higher payments. The provider may request an in-force illustration or other information from the insurance company to evaluate future premium requirements.
Policy Type and Guarantees
Universal life, guaranteed universal life, whole life, survivorship, and certain term policies may qualify for a life settlement.
The specific provisions and guarantees within the policy matter. For example, a convertible term policy may have settlement potential when it can still be converted to permanent insurance. A nonconvertible term policy is much less likely to qualify.
If you own convertible term insurance, consider having it evaluated before the conversion period expires.
Is My Policy Worth More Than Its Cash Surrender Value?
Cash surrender value is determined by the insurance contract. Life settlement value is based on what a purchaser is willing to pay for the policy.
Because life settlement vs surrender value are two different calculations, a qualifying policy may have a settlement value greater than its cash surrender value. A policy with little or even no cash surrender value may still have value in the secondary market.
This distinction is particularly important for policy owners considering surrendering a policy or allowing it to lapse. Before giving up a policy, it is worth checking into whether it qualifies for a life settlement.
Can I Find My Life Insurance Policy’s Value on My Statement?
Your policy statement may show useful information such as the death benefit, accumulated cash value, surrender value, and current premium. It does not normally show what the policy could be worth in a life settlement.
Settlement value is not established by the insurance carrier. It requires a separate evaluation based on the policy and the insured’s current circumstances.
A recent policy statement can be a useful starting point, but additional information will generally be required before a provider can determine whether an offer is available.
Does a Policy Have to Have Cash Value to Be Sold?
Cash value and life settlement value are not the same thing and many times policies with little to no cash value qualify.
For example, term life insurance typically does not accumulate cash value. However, some term policies may qualify for a life settlement when they include a conversion option that allows the policy to be converted to permanent insurance.
Likewise, a permanent policy with minimal cash surrender value may still qualify. Whether it has settlement value depends on the complete evaluation rather than its cash account alone.
Can a Life Settlement Calculator Tell Me What My Policy Is Worth?
A simple calculator cannot determine the actual market value of a life insurance policy. While these calculators can be helpful, they typically provide a range of potential value rather than actually calculating the exact amount someone may be willing to offer you.
Age and death benefit can provide some initial context, but they leave out information that can substantially affect an offer. Health, future premiums, policy guarantees, conversion provisions, and other policy details all need to be considered.
The most reliable way to determine whether a policy has settlement value is to have the actual policy and insured evaluated.
How Do I Find Out What My Life Insurance Policy Is Worth?
Start with a recent policy statement and basic information about the insured. A life settlement provider can then determine whether the policy appears likely to qualify and identify any additional information needed for a complete evaluation.
Medical records and information obtained from the insurance carrier may be required before an offer can be determined. Requesting an evaluation does not mean you have to sell the policy. If an offer is available, you can review it and decide whether selling makes sense for you.
Find Out What Your Life Insurance Policy May Be Worth
Settlement Group works directly with policy owners to evaluate life insurance policies for potential life settlements.
If you are considering surrendering, lapsing, or selling a life insurance policy, a no-obligation review can help you determine whether the policy may have value beyond what the insurance company will pay to surrender it.
Contact Settlement Group for a no-obligation policy review. 912-882-0840